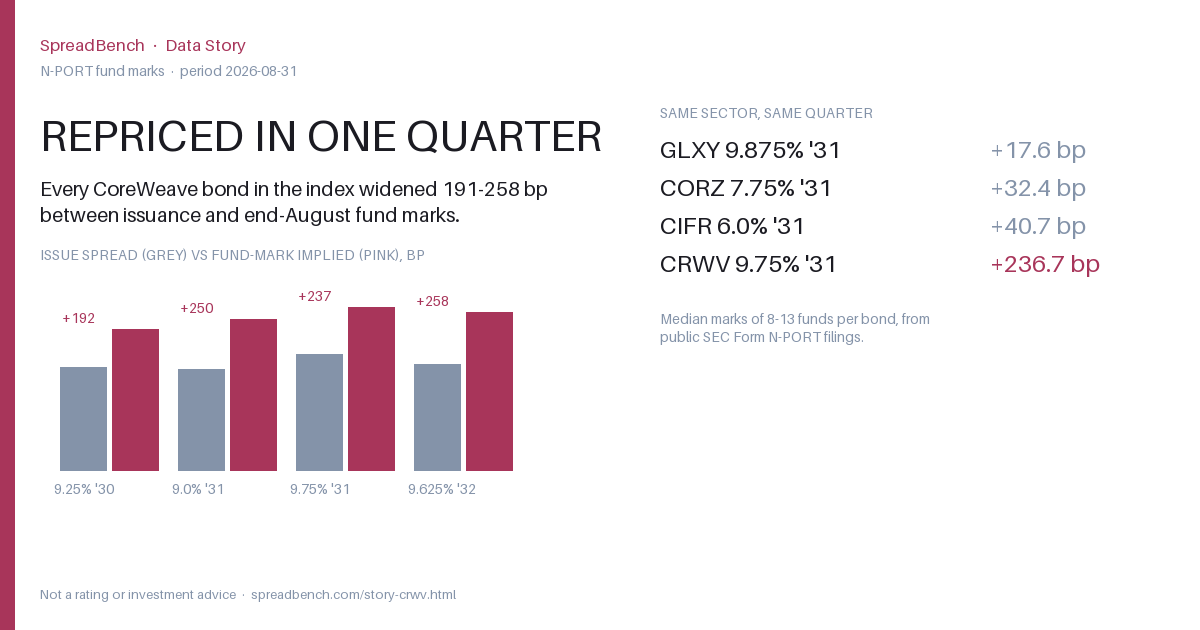
At issuance, coupon minus Treasury gave 506-581bp. At 2026-08-31, quarter-end fund marks solve to 709-818bp — a face-value-weighted 231bp wider across the four bonds. In the same quarter, in the same sector, Galaxy Digital / Core Scientific / Cipher Mining widened only 17.6 / 32.4 / 40.7bp. That gap is the story.
| Bond | Pricing date | Face value | Median price | Issue spread | Implied | Δ | Funds |
|---|---|---|---|---|---|---|---|
| CRWV 9.25% '30 | 2025-05-19 | $2,000M | 92.87 | 517.7 bp | 709.2 bp | +191.5 | 8 |
| CRWV 9.0% '31 | 2025-07-22 | $1,750M | 89.71 | 506.4 bp | 756.3 bp | +249.9 | 9 |
| CRWV 9.75% '31 | 2026-04-15 | $2,750M | 89.42 | 580.8 bp | 817.5 bp | +236.7 | 13 |
| CRWV 9.625% '32 | 2026-06-18 | $1,250M | 88.27 | 533.6 bp | 791.3 bp | +257.7 | 11 |
| Bond | Issue spread | Implied | Δ |
|---|---|---|---|
| Galaxy Digital 9.875% '31 | 544.4 bp | 562.0 bp | +17.6 |
| Core Scientific 7.75% '31 | 376.1 bp | 408.5 bp | +32.4 |
| Cipher Mining 6.0% '31 | 173.9 bp | 214.6 bp | +40.7 |
| CoreWeave 9.75% '31 | 580.8 bp | 817.5 bp | +236.7 |
N-PORT reports the fair value (mostly Level 2) a fund assigns to each holding at quarter-end — not a secondary-market traded price. It carries a lag (filed within 60 days of period end) and each manager's own valuation approach, which is why we take the cross-fund median to suppress single-manager noise.
One step: given the median price, coupon and maturity, solve for YTM and subtract the matched Treasury interpolation. Everything is public, so anyone with the same price gets the same spread.
"Why CoreWeave specifically" is not what this page answers — that needs holdings structure, covenant detail and customer concentration. This page does one thing: place two sets of public numbers next to each other. The conclusion is yours.
Share card (ready to post): story-crwv.png · data endpoint GET /api/v1/real/marks.json