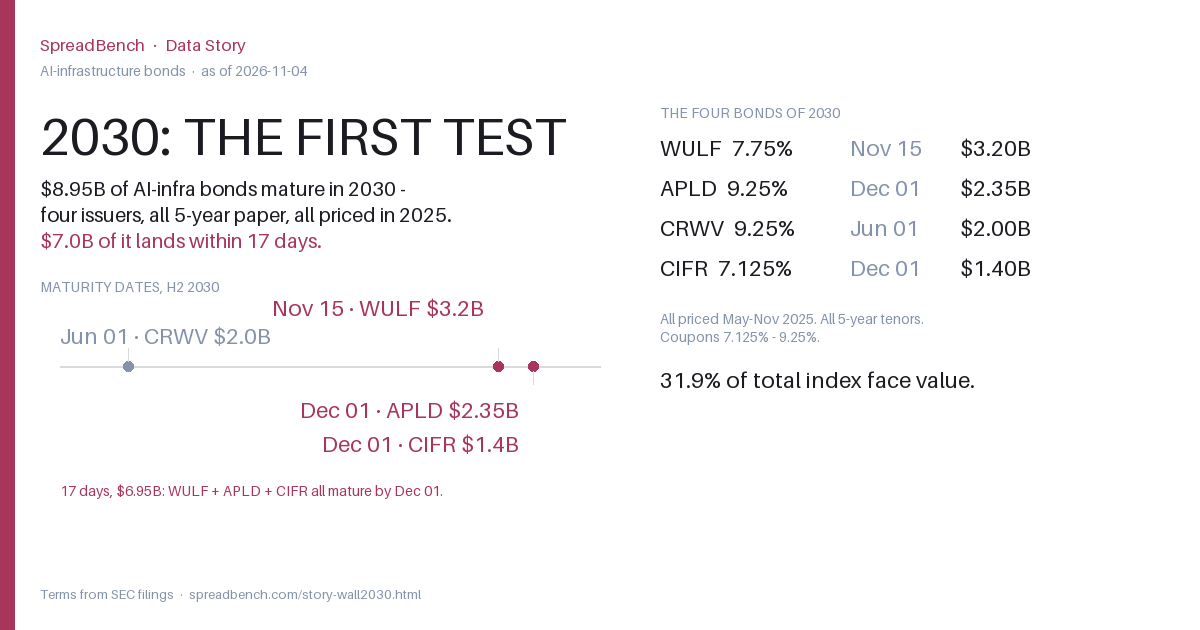
Everyone watches the $17.9B wall in 2031. The market meets this cohort earlier — in 2030. Four bonds, four different issuers, $8.95B of face value (31.9% of the index). Their common features are even tidier than 2031's: all straight 5-year paper, every one priced between May and November 2025 — and $6.95B lands inside a 17-day window between 15 November and 1 December 2030.
Note: APLD and CIFR both mature on 2030-12-01, so their markers nearly coincide — which is exactly the point of the chart.
| Issuer | Coupon / maturity | Face value | Structure | Tenor | Issue spread | Pricing date | Fund mark |
|---|---|---|---|---|---|---|---|
| CoreWeave CRWV 9.25% '30 | 2030-06-01 | $2,000M | Unsecured | 5.0y | 517.7 bp | 2025-05-19 | 709.2 bp (+191.5) |
| TeraWulf WULF 7.75% '30 | 2030-11-15 | $3,200M | Secured | 5.0y | 402.6 bp | 2025-10-30 | — |
| Applied Digital APLD 9.25% '30 | 2030-12-01 | $2,350M | Secured | 5.0y | 550.6 bp | 2025-11-14 | — |
| Cipher Mining CIFR 7.125% '30 | 2030-12-01 | $1,400M | Secured | 5.0y | 342.9 bp | 2025-11-06 | — |
Every one of the four is a straight 5.0-year issue (CRWV 5.0 / WULF 5.0 / APLD 5.0 / CIFR 5.1), priced between May and November 2025. One issuance window, one tenor choice — so their maturities are structurally locked into H2 2030. That is not coincidence, it is the result of a shared funding preference.
WULF's $3.2B matures on 15 November; APLD's $2.35B and CIFR's $1.4B both on 1 December. Three independent issuers, two dates, one 17-day window — for the market this is not one company's refinancing, it is a quarter's concentrated supply. The 2031 wall is taller, but 2030 arrives first.
Only CRWV 9.25% '30 (the sole unsecured bond here) has an N-PORT quarterly mark: issued at 517.7bp, fund marks imply 709.2bp at 2026-08-31, i.e. 191.5bp wider. The other three have no reported fund holdings yet, and we do not fill in estimates — if there is no data, there is no number.
Share card (ready to post): story-wall2030.png · data endpoint GET /api/v1/real/universe.json