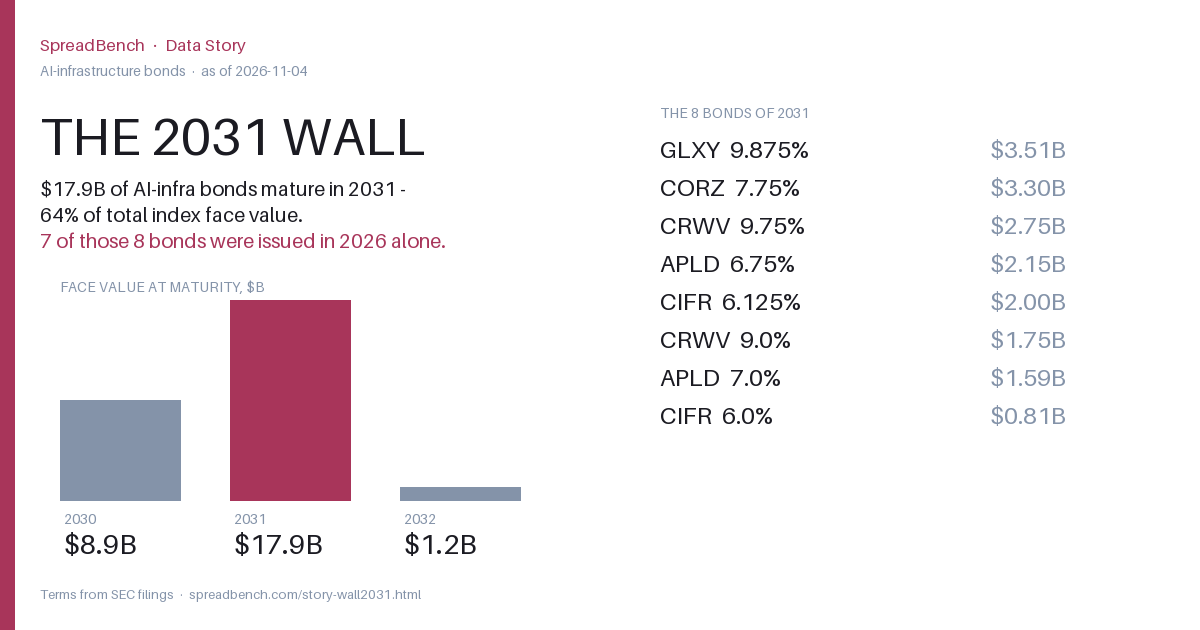
Eight of the 13 AI-infrastructure bonds in the index mature in the same year — 2031, $17.86B of face value, 63.6% of the whole index. The total is not the interesting part. The speed is: 7 of those 8 were issued in 2026, $16.1B of them. Every number below links back to an SEC filing.
| Issuer | Coupon / maturity | Face value | Structure | Issue spread | Pricing date |
|---|---|---|---|---|---|
| Galaxy Digital GLXY 9.875% '31 | 2031-08-01 | $3,507M | Secured | 544.4 bp | 2026-07-24 |
| Core Scientific CORZ 7.75% '31 | 2031-05-01 | $3,300M | Secured | 376.1 bp | 2026-05-06 |
| CoreWeave CRWV 9.75% '31 | 2031-10-01 | $2,750M | Unsecured | 580.8 bp | 2026-04-15 |
| Applied Digital APLD 6.75% '31 | 2031-03-01 | $2,150M | Secured | 308.1 bp | 2026-03-04 |
| Cipher Mining CIFR 6.125% '31 | 2031-03-01 | $2,000M | Secured | 237.8 bp | 2026-02-05 |
| CoreWeave CRWV 9.0% '31 | 2031-02-01 | $1,750M | Unsecured | 506.4 bp | 2025-07-22 |
| Applied Digital APLD 7.0% '31 | 2031-06-15 | $1,590M | Secured | 284.0 bp | 2026-06-16 |
| Cipher Mining CIFR 6.0% '31 | 2031-06-15 | $810M | Secured | 173.9 bp | 2026-06-09 |
Seven of the eight bonds priced between February and July 2026 — $16.11B of face value. This is not five years of issuance piling up; it is a single issuance window that produced a batch of same-maturity paper, so their refinancing dates collide structurally.
All $4.5B of unsecured face value maturing in 2031 belongs to CoreWeave (9.0% '31 and 9.75% '31). The other $13.36B is secured paper across GLXY / CORZ / APLD / CIFR. Different structures mean the same year's "wall" looks completely different depending on what you hold.
"Can it roll the 2031 maturities?" requires cash-flow models, indenture detail and private financials — outside the boundary of public data. This site does two verifiable things: what the terms are, and when the bonds come due.
Share card (ready to post): story-wall2031.png · data endpoint GET /api/v1/real/universe.json